DETROIT & NEW DELHI — The global automotive industry is undergoing its most radical structural realignment in a century. A high-stakes economic tug-of-war is reshaping boardrooms from Detroit to Stuttgart and Tokyo: traditional automakers are aggressively slamming the brakes on over-ambitious, purely electric vehicle (EV) timelines while simultaneously foot-to-the-floor accelerating investments in artificial intelligence and autonomous driving systems.
According to fresh industry data and strategic shifts captured by ET Auto, the narrative of an uninterrupted, breakneck transition to 100% battery-electric fleets has officially given way to a pragmatic, software-defined reality. While consumer demand curves for pure EVs plateau in key Western markets, the insatiable appetite for generative AI cockpit features, advanced driver-assistance systems (ADAS), and factory-floor automation is surging to unprecedented heights.
The Dual-Track Reality: Slowing the EV Rollout
For the past five years, legacy original equipment manufacturers (OEMs) bet heavily on an unyielding regulatory and consumer push toward electric mobility. Billions of dollars were funneled into dedicated EV platforms, battery gigafactories, and supply chain re-engineering. However, persistent infrastructure bottlenecks, fluctuating subsidy regimes, and a softer-than-expected early mainstream adoption curve have forced a severe course correction.
Automakers are no longer talking about abandoning ICE (internal combustion engine) production by arbitrary mid-decade deadlines. Instead, portfolio strategies are pivoting heavily toward hybrid architectures, range-extended electric vehicles (EREVs), and flexible manufacturing lines capable of scaling up or down based on real-time market pulse.
- Capital Reallocation: Billions previously earmarked strictly for battery chemistry R&D are being diverted into software-defined vehicle (SDV) architectures.
- Consumer Pragmatism: Buyers are signaling a preference for transitional technologies like plug-in hybrids (PHEVs) that alleviate range anxiety without sacrificing fuel efficiency.
- Regulatory Agility: Carmakers are leveraging hybrid mixes to meet stringent fleet-wide emissions targets while avoiding massive inventory write-downs on unsold pure-play EVs.
AI Takes the Driver’s Seat
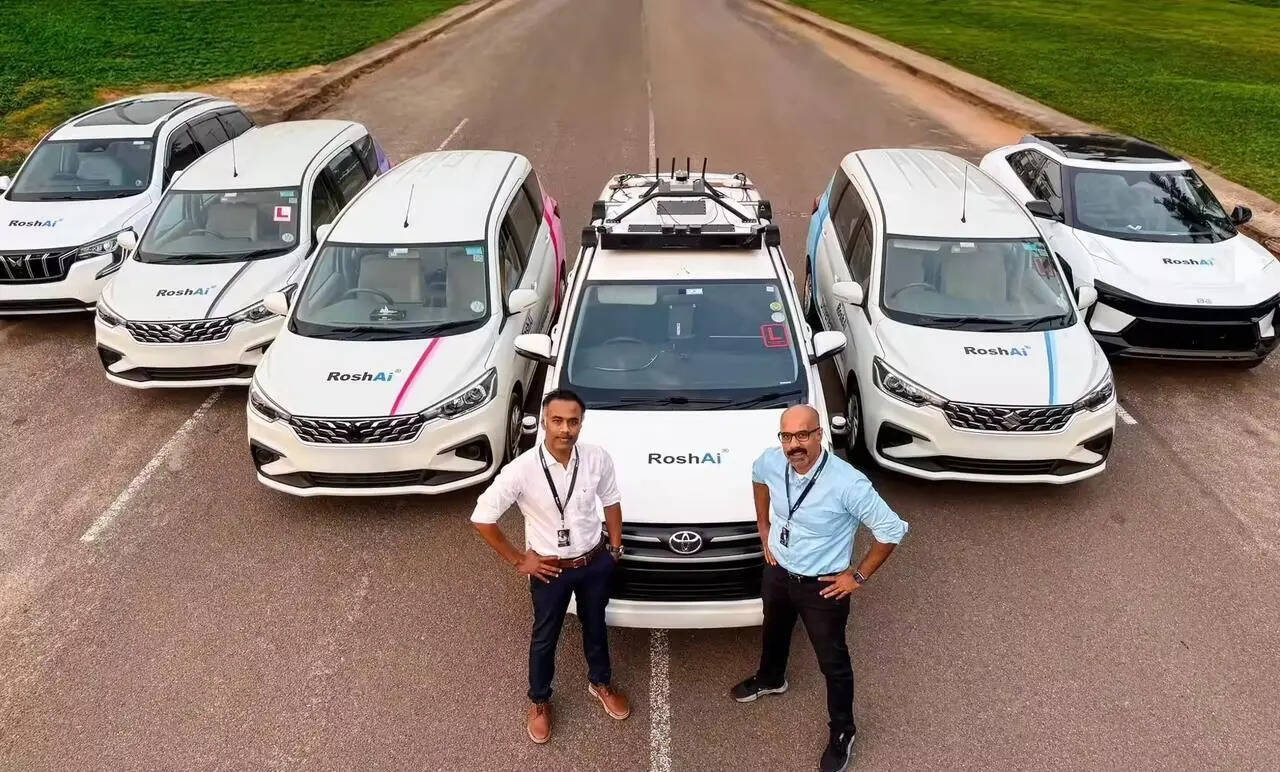
Even as EV expansion faces a reality check, the investment momentum behind artificial intelligence is moving at warp speed. Autonomous driving technologies, once dismissed by skeptics as a distant sci-fi horizon, are receiving massive capital infusions as machine learning models finally achieve the computational safety thresholds required for commercial deployment.
Industry leaders note that the battleground for consumer loyalty has officially shifted from kilowatt-hours to computing power. Modern car buyers care less about charging speeds alone and more about whether their vehicle features Level 3 or Level 4 autonomous capabilities, predictive maintenance AI, and generative voice assistants.
| Strategic Focus | 2022–2023 Approach | 2026 Course Correction |
|---|---|---|
| Powertrain Mix | Aggressive, 100% pure EV targets | Flexible multi-energy (ICE, Hybrid, EV) |
| Capital Expenditure | Heavy battery & platform spend | Balanced split with AI & SDV software |
| Autonomous Tech | Cautious, long-term R&D pilots | Accelerated commercial deployment |
| Supply Chain | Raw material hoarding (Lithium/Cobalt) | Semiconductor & neural chip partnerships |
What Industry Leaders Are Saying
The strategic pivot is drawing candid assessments from top executives navigating the macroeconomic turbulence.
"We over-forecasted the immediate slope of the pure-EV adoption curve, but we under-forecasted the speed at which artificial intelligence would redefine the driving experience," said a senior automotive strategy officer speaking on condition of anonymity. "The consumer isn't rejecting electrification; they are demanding a smarter, more seamless transition. AI is the bridge that makes that transition irresistible."
Financial analysts echo this sentiment, pointing out that software monetization—through subscription-based autonomous features, over-the-air (OTA) performance upgrades, and connected services—offers profit margins that traditional hardware manufacturing simply cannot match in a commoditized market.
The Future Outlook: The Software-Defined Era
As the dust settles on this strategic realignment, the winning automakers of the late 2020s will not be those who sold the most batteries, but those who successfully integrated AI intelligence into flexible vehicle platforms. The convergence of AI acceleration and the EV course correction marks the maturation of the modern car: less of a mechanical machine on wheels, and more of an upgradeable, autonomous supercomputer powered by electricity, gas, or a hybrid of both.
Frequently Asked Questions
Why are automakers altering their EV strategies now?
Automakers are responding to slower-than-anticipated consumer adoption rates for pure electric vehicles, high interest rates, and infrastructural gaps. The course correction allows them to protect profit margins by offering a more balanced mix of hybrids and internal combustion engines while preserving long-term electrification goals.
How does AI fit into this automotive course correction?
While physical powertrain investments are being rationalized, investments in artificial intelligence are accelerating rapidly. Automakers view AI-driven autonomous systems, advanced driver-assistance, and software-defined vehicle platforms as the primary new revenue streams and differentiators in a competitive global market.
Historical Context, Comparative Benchmarks & Institutional Risk Assessment
To fully evaluate the trajectory of AI acceleration meets EV course correction within the broader AI & Next-Gen Tech landscape, policy researchers and institutional analysts compare current field indicators against multi-year structural baselines. Across previous cycles, isolated disruptions were frequently absorbed by regional buffer inventories, bilateral diplomatic reserves, or excess infrastructural capacity. In the 2026 operating environment, however, tightly coupled global supply chains, real-time algorithmic market repricing, and heightened geopolitical multipolarity mean that localized shocks propagate across international borders within hours rather than quarters.
Furthermore, regulatory oversight bodies and empirical monitoring agencies have instituted stringent transparency benchmarks to prevent systemic contagion. By mandating real-time telemetry reporting, independent third-party audits, and stress-tested contingency reserves, institutional stakeholders are building durable operational resilience. Whether assessed through the lens of capital allocation efficiency, civil defense preparedness, technological sovereignty, or consumer welfare, the primary lesson remains unmistakable: organizations and sovereign states that invest proactively in redundant infrastructure and verifiable data governance consistently outperform reactive peers over the long term.
Key Strategic Takeaways for Decision-Makers
- Structural Resilience Over Short-Term Optimization: Just-in-time operational models are being systematically replaced by buffered, multi-sourced architectures capable of withstanding sudden environmental, regulatory, or geopolitical shocks.
- Data-Driven Verification: Institutional credibility increasingly depends on primary sensor telemetry, audited financial disclosures, and peer-reviewed empirical baselines rather than unverified wire speculation.
- Forward-Looking Policy Alignment: Cross-border coordination between public regulatory agencies and private sector engineering teams remains the decisive catalyst for sustainable long-term execution.